
Going from living in a van to owning a duplex took less than five years, and it happened through two moves rather than a plan. First I moved into a van to escape rent in a high-cost coastal city. Then I moved to the Midwest, where a starter home cost roughly $185,000 instead of the roughly $700,000 back home. A small house came first, the duplex three years later.
New to the strategy behind this story? Start with what house hacking is.
Five years, and two desperate moves with no master plan.
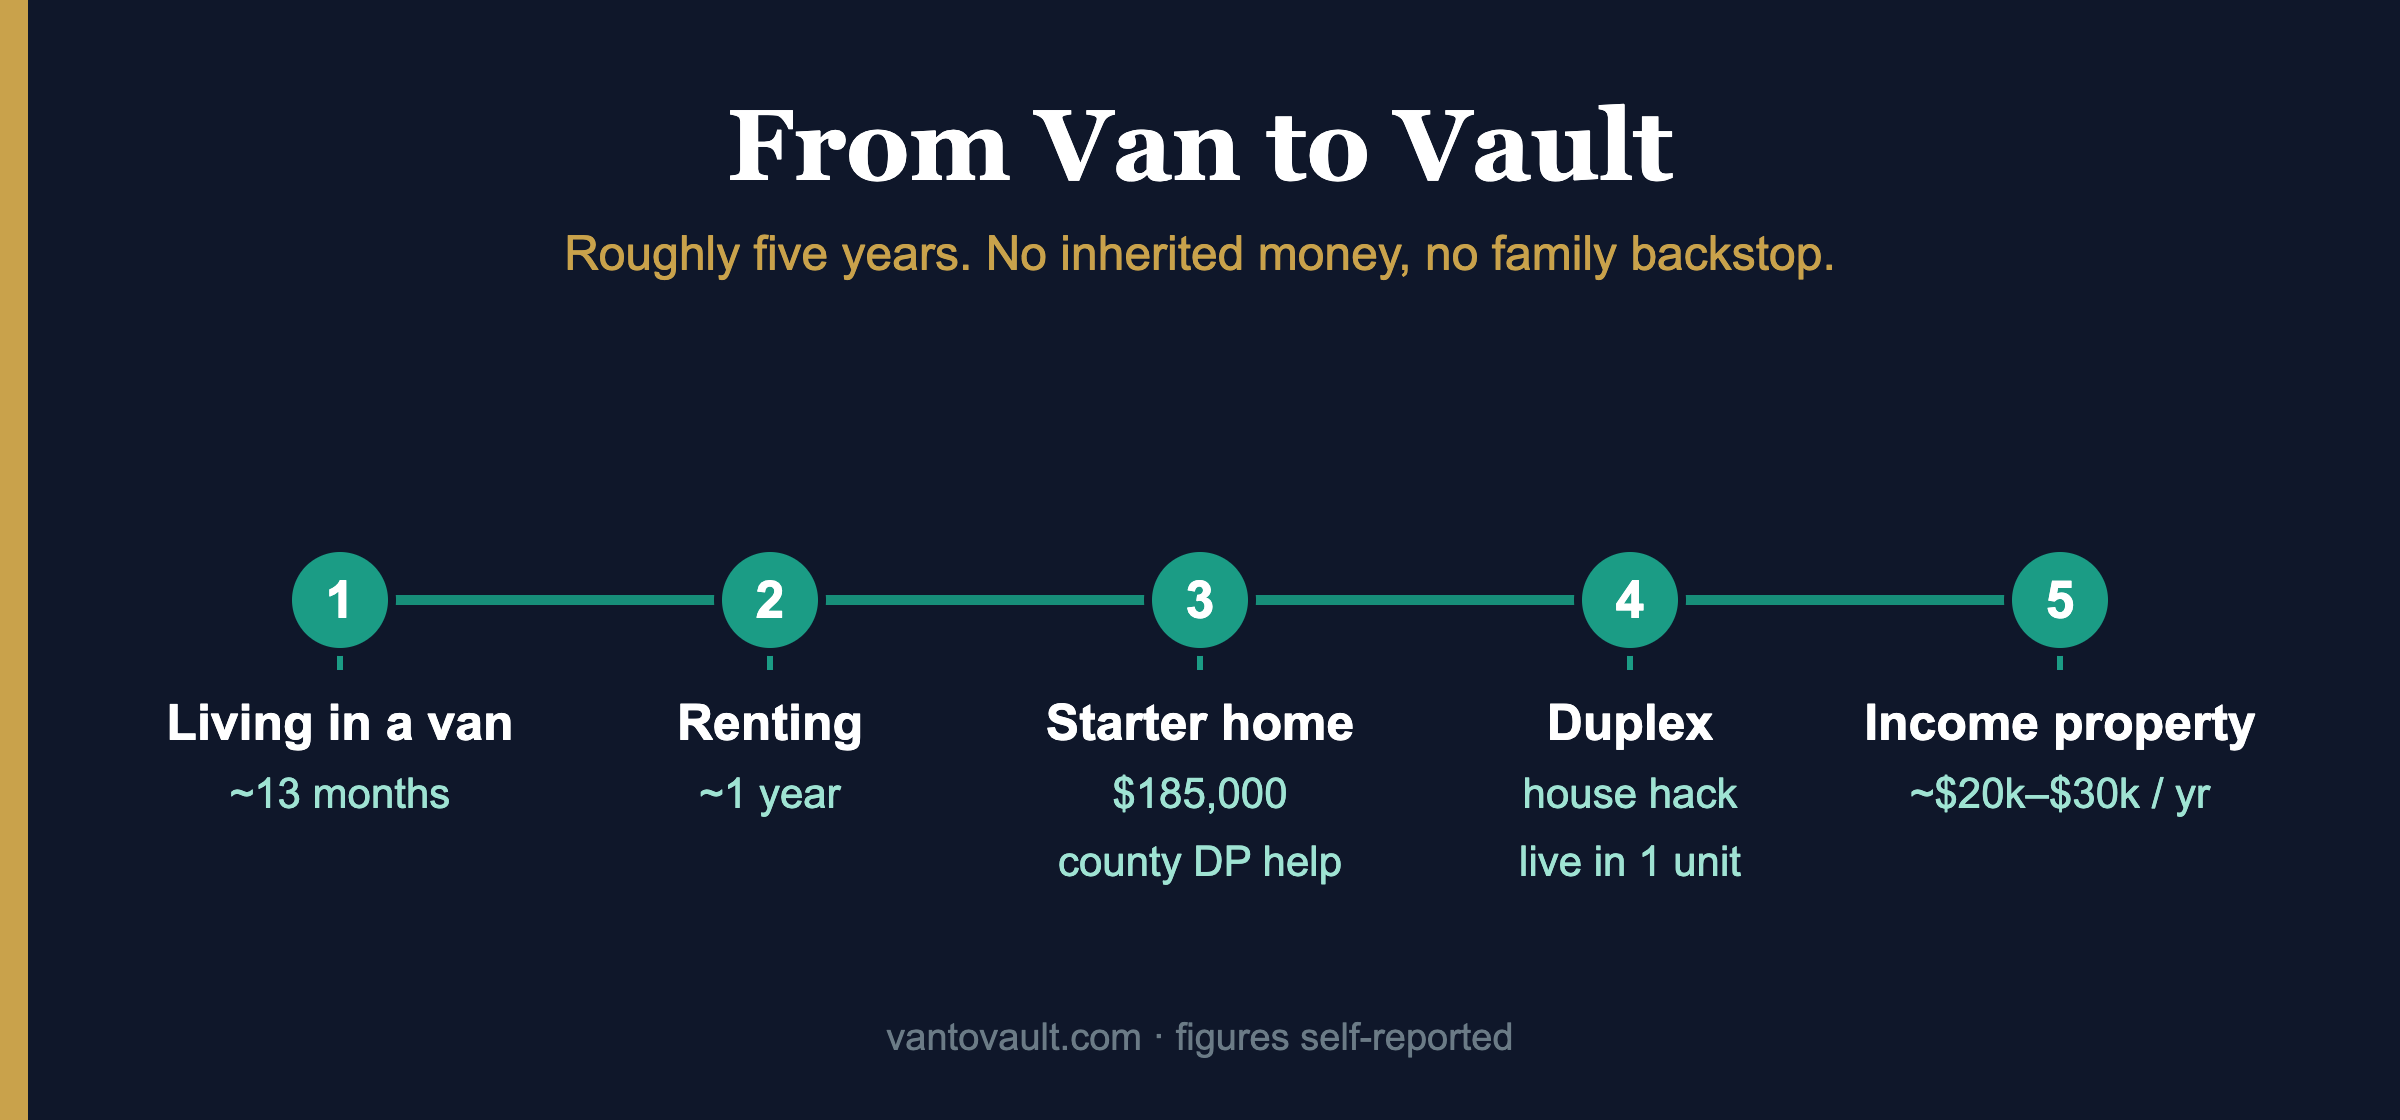
People ask me how long it took to go from sleeping in a van to owning a small multi-family. The technical answer is “less than five years, but not the way you’d think.”
The story that fits in an Instagram caption is I figured out the math, executed a plan, and crossed the finish line. That’s not actually what happened, and I suspect something that simple leaves out key details (like mom and dad gave me a down payment).
What really happened is closer to: I bumped into one good idea, made a big sacrifice, took a couple of baby steps, and stayed cheap for longer than was fun.
Here is the full story, one that maybe you might glean some useful insight from:
Move 1: into the van (no plan)
I’d believed the standard American Dream story I’d grown up with: work hard, save 10%, the rest takes care of itself. I tried it. I was 20-something, in a high-cost coastal city, working a dead-end job that paid an average wage. The math did not work. After rent, food, and a car payment, there was no 10% left to save. Some months it was 0% left to save, most months it was increased debt, which is even worse.
So I got a little desperate, and started making drastic changes in hopes that something would give me the angle I needed to break out of the poverty I was in. First one was moving into a van.
What living in a van was actually like
In order to afford the van, I sold my crappy car, which barely helped at all, and took out more debt. This was justified as the cost of the debt was lower than renting, which was an exorbitant cost.
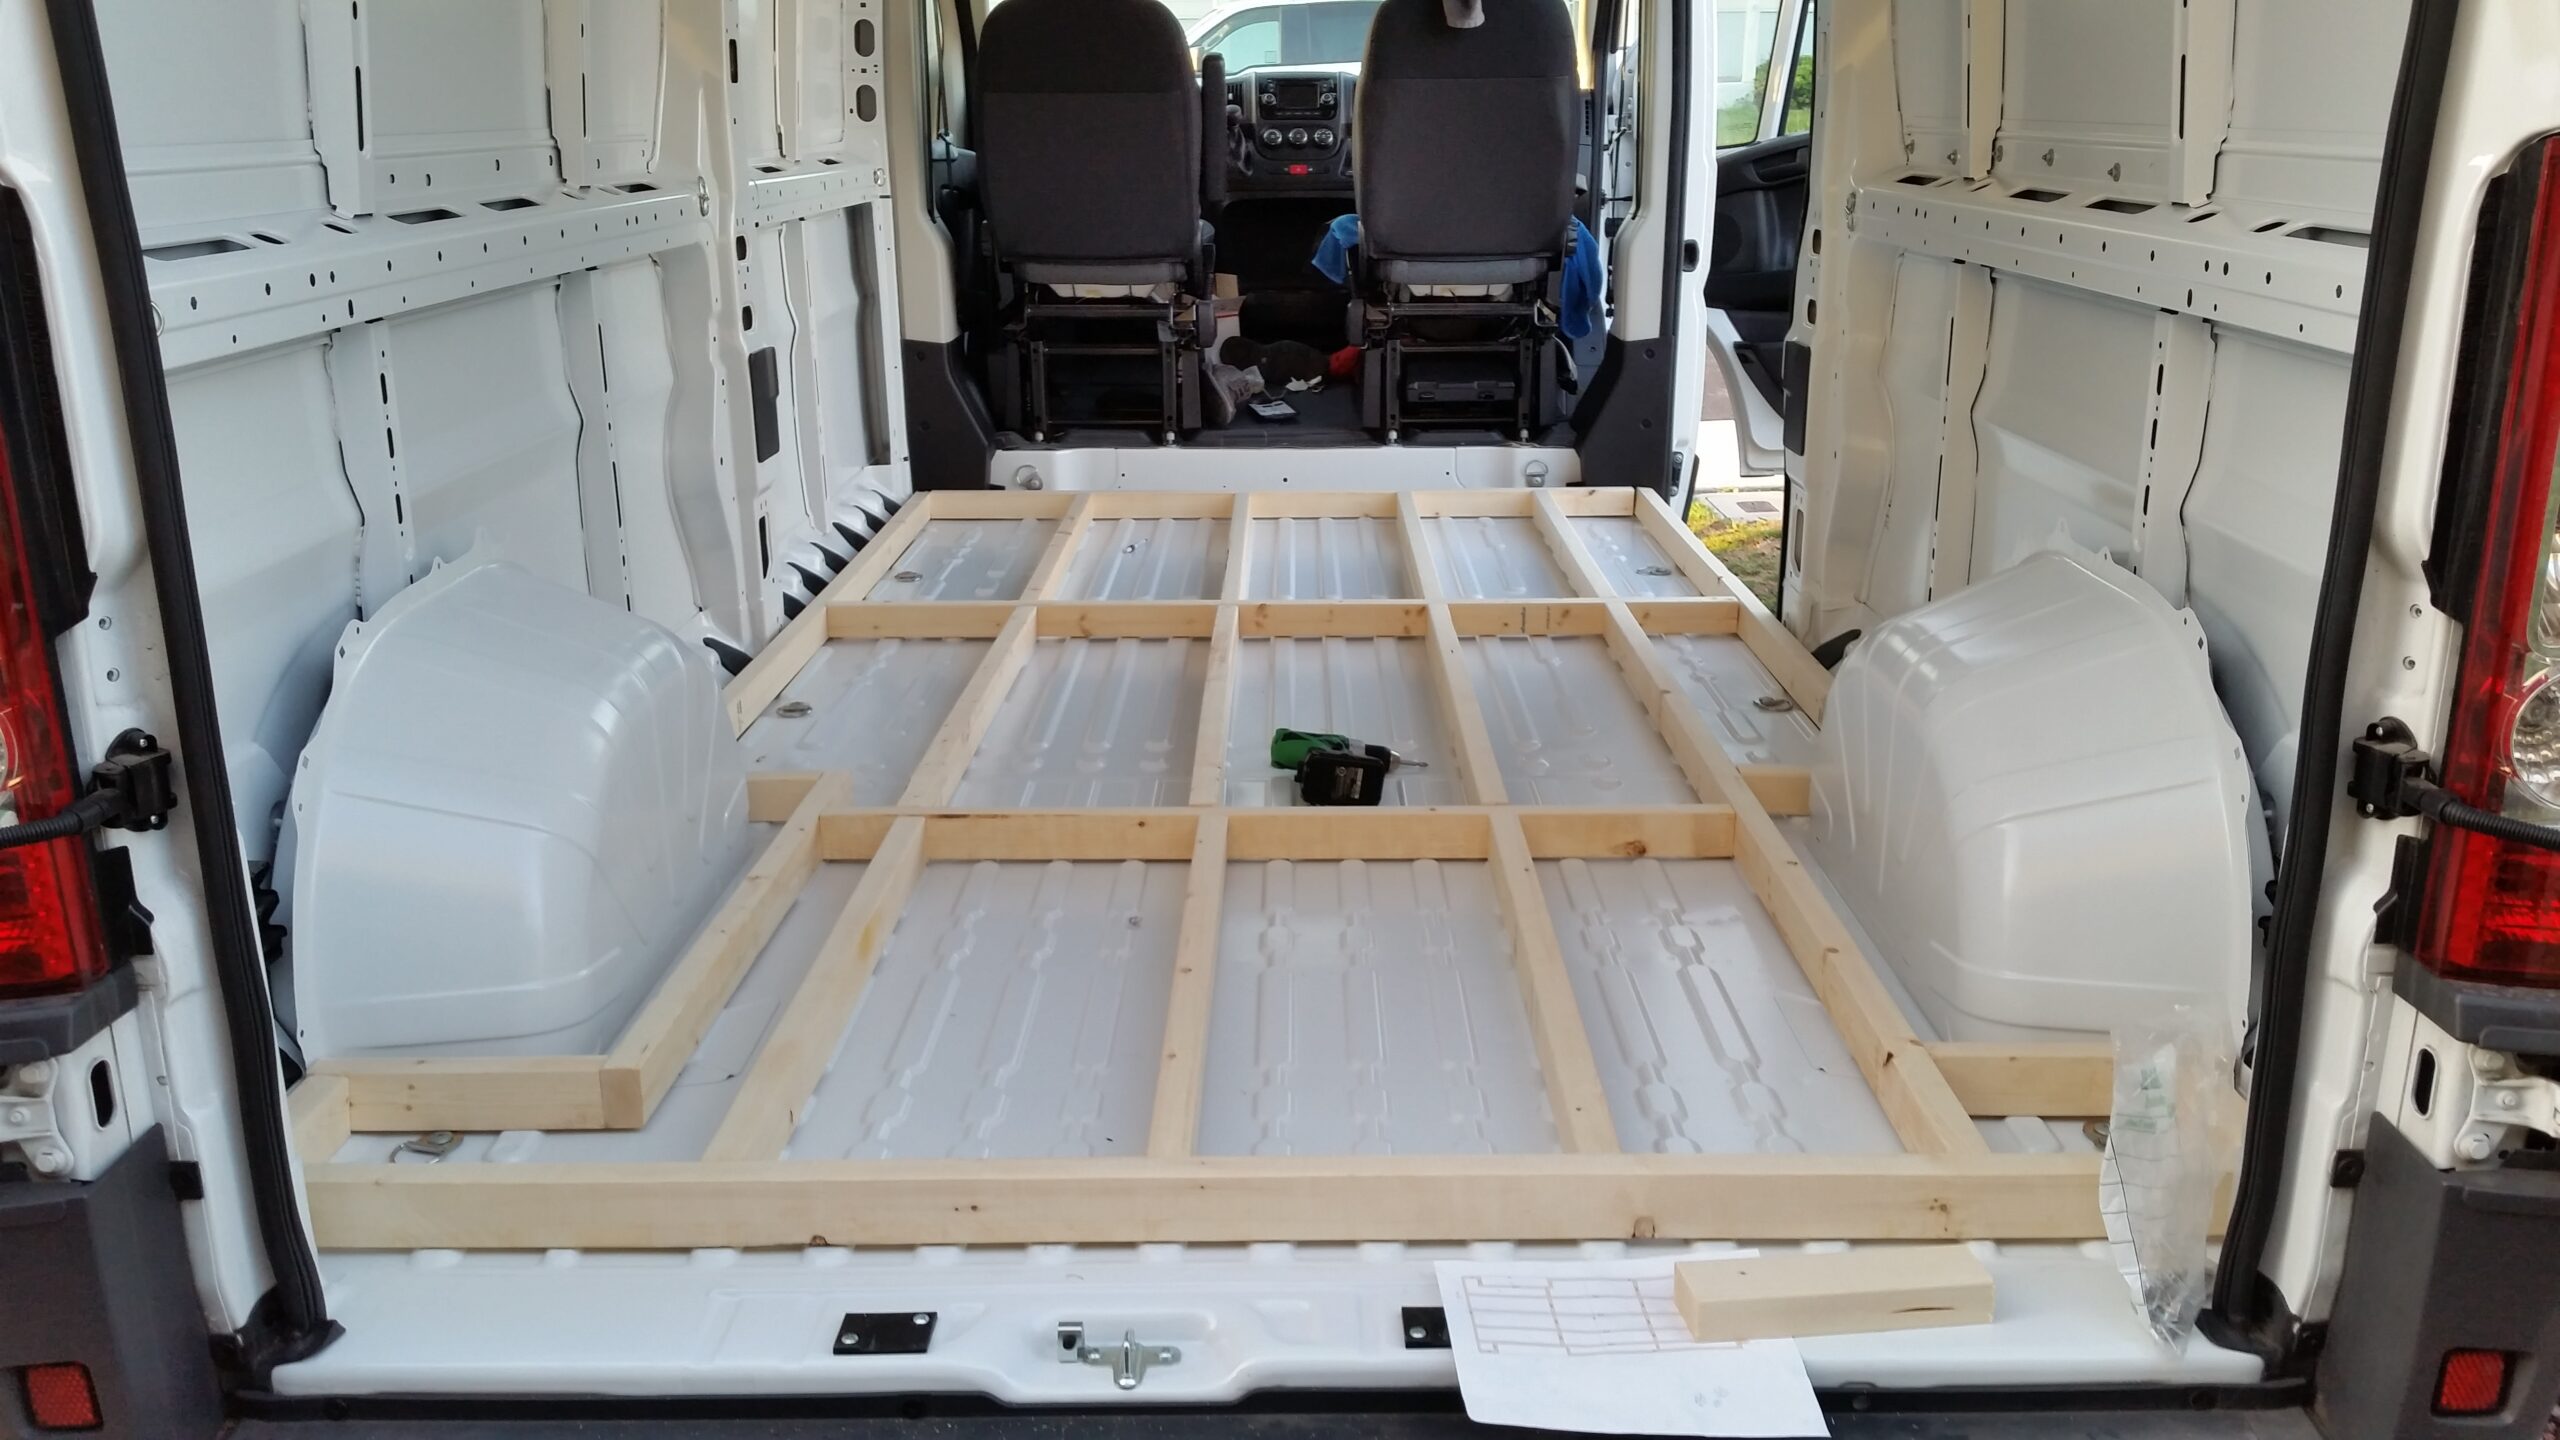
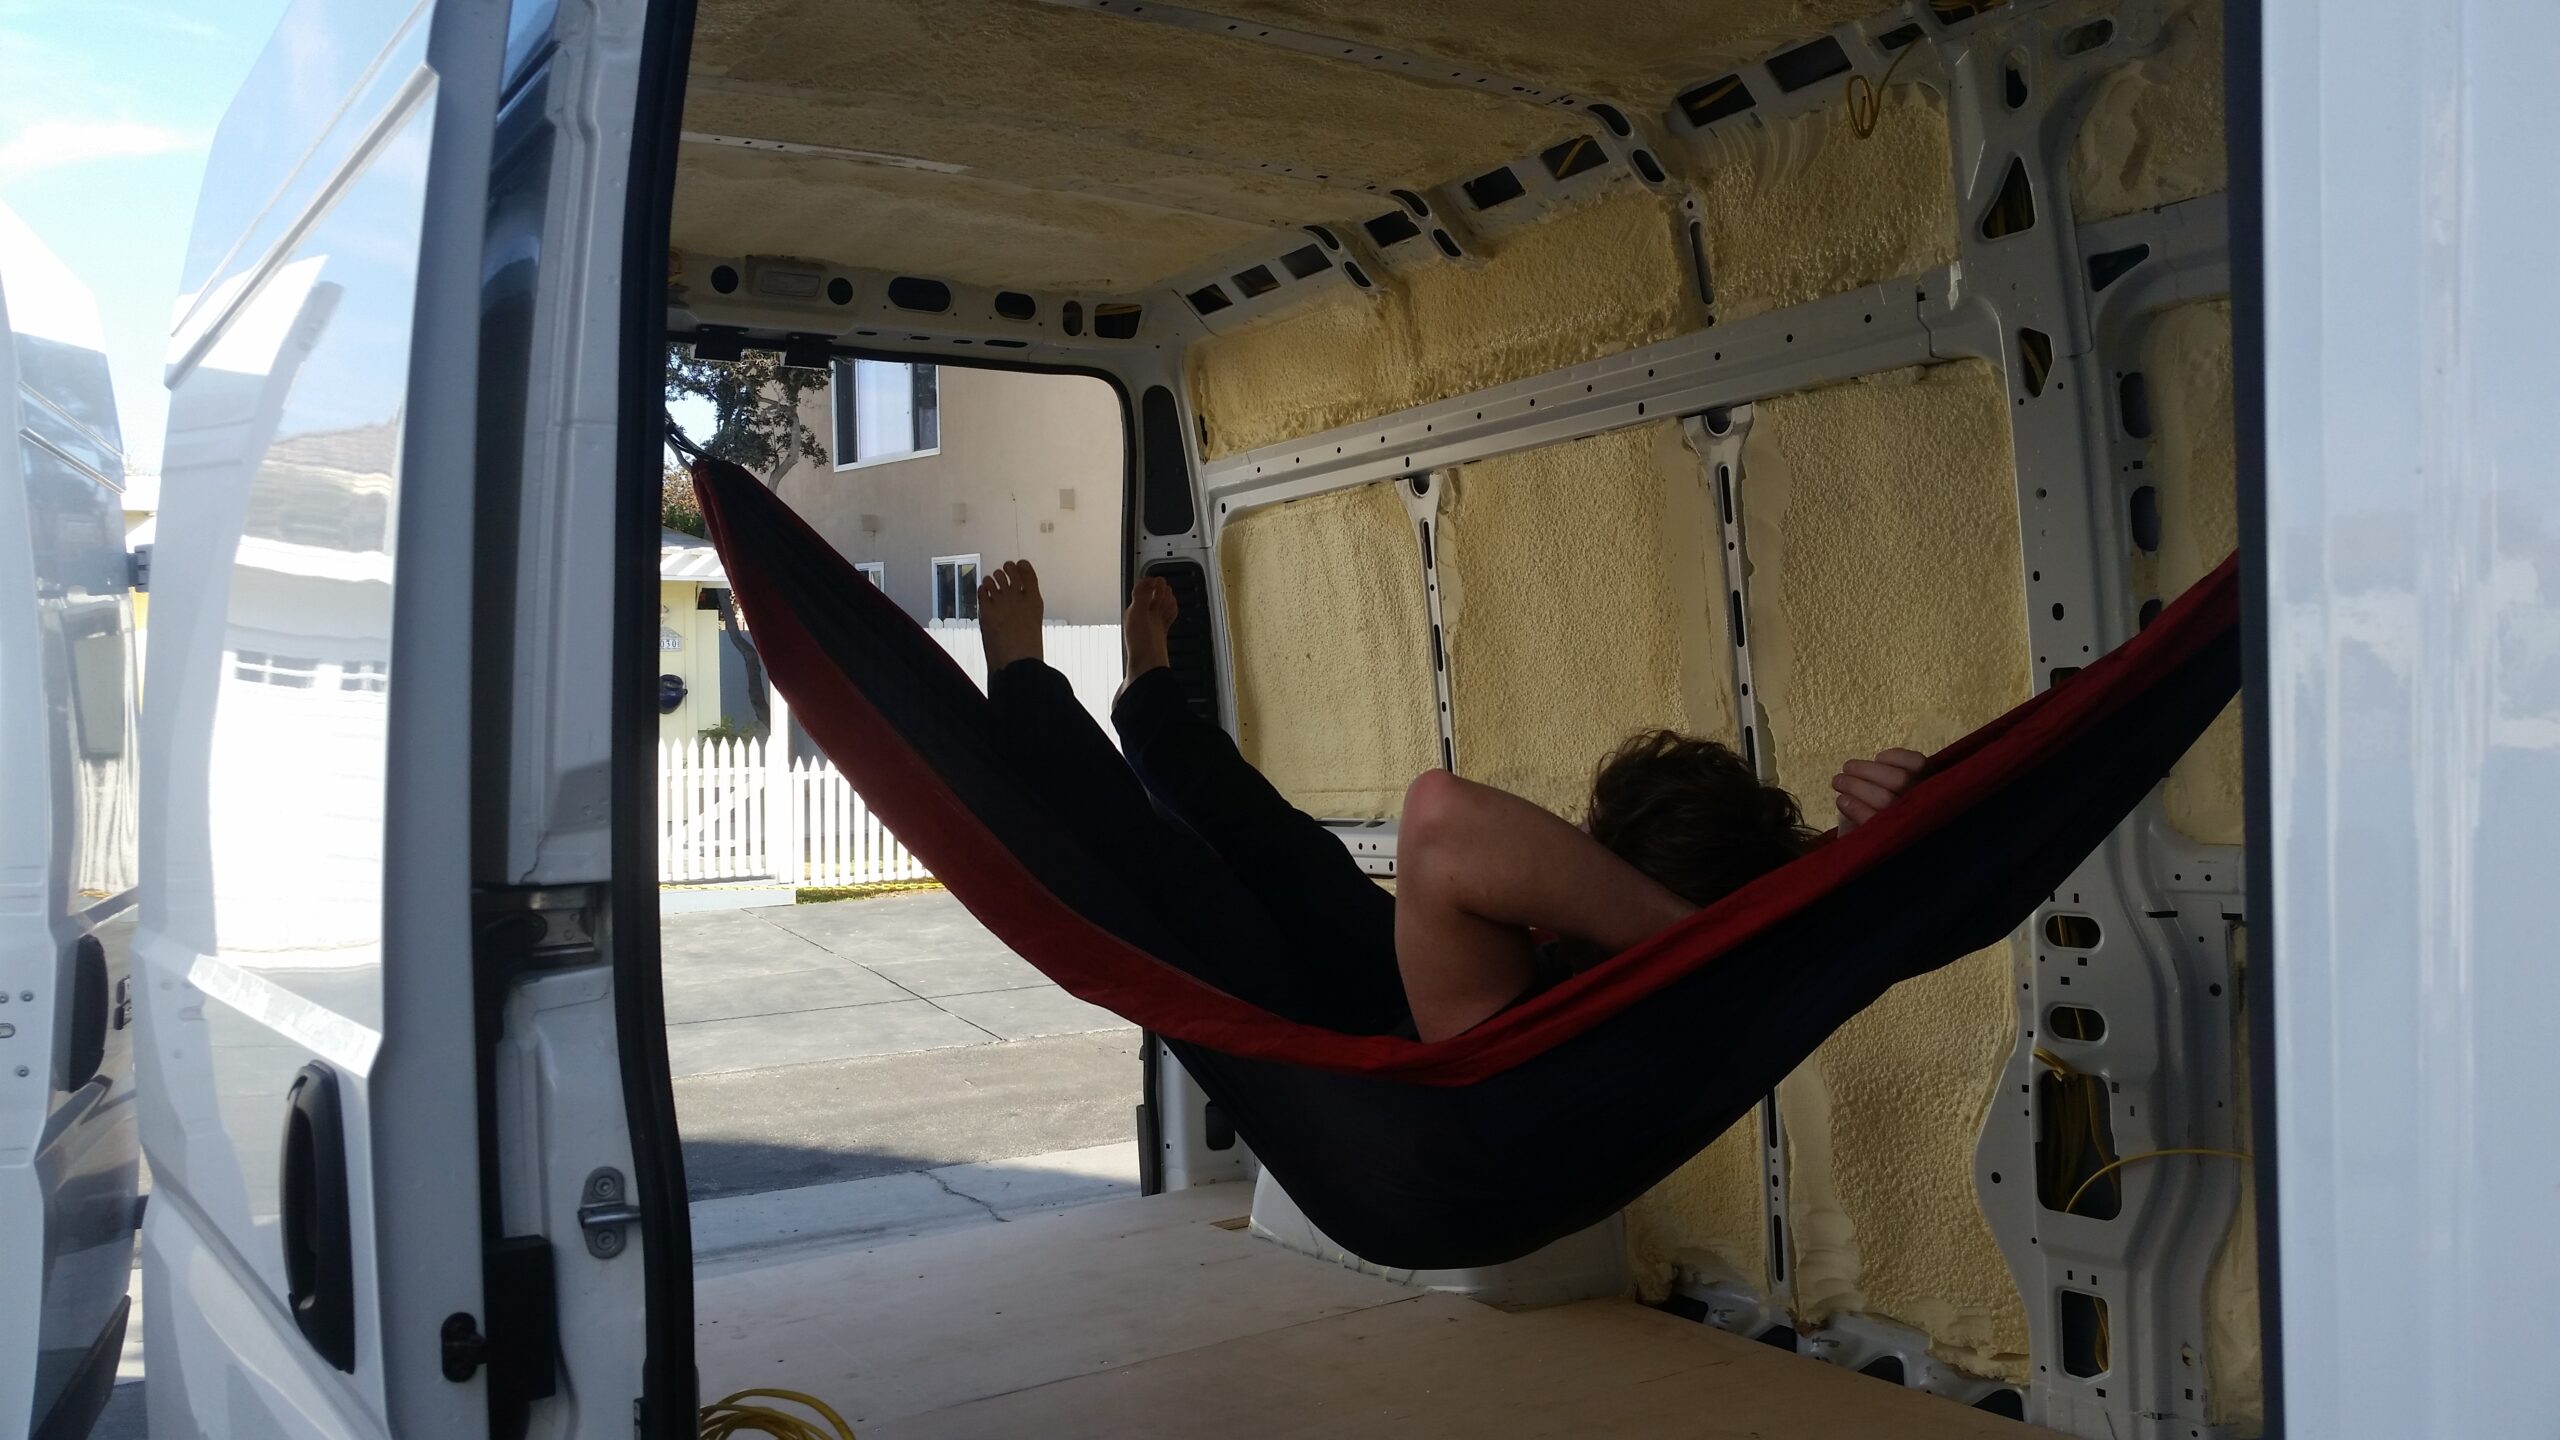
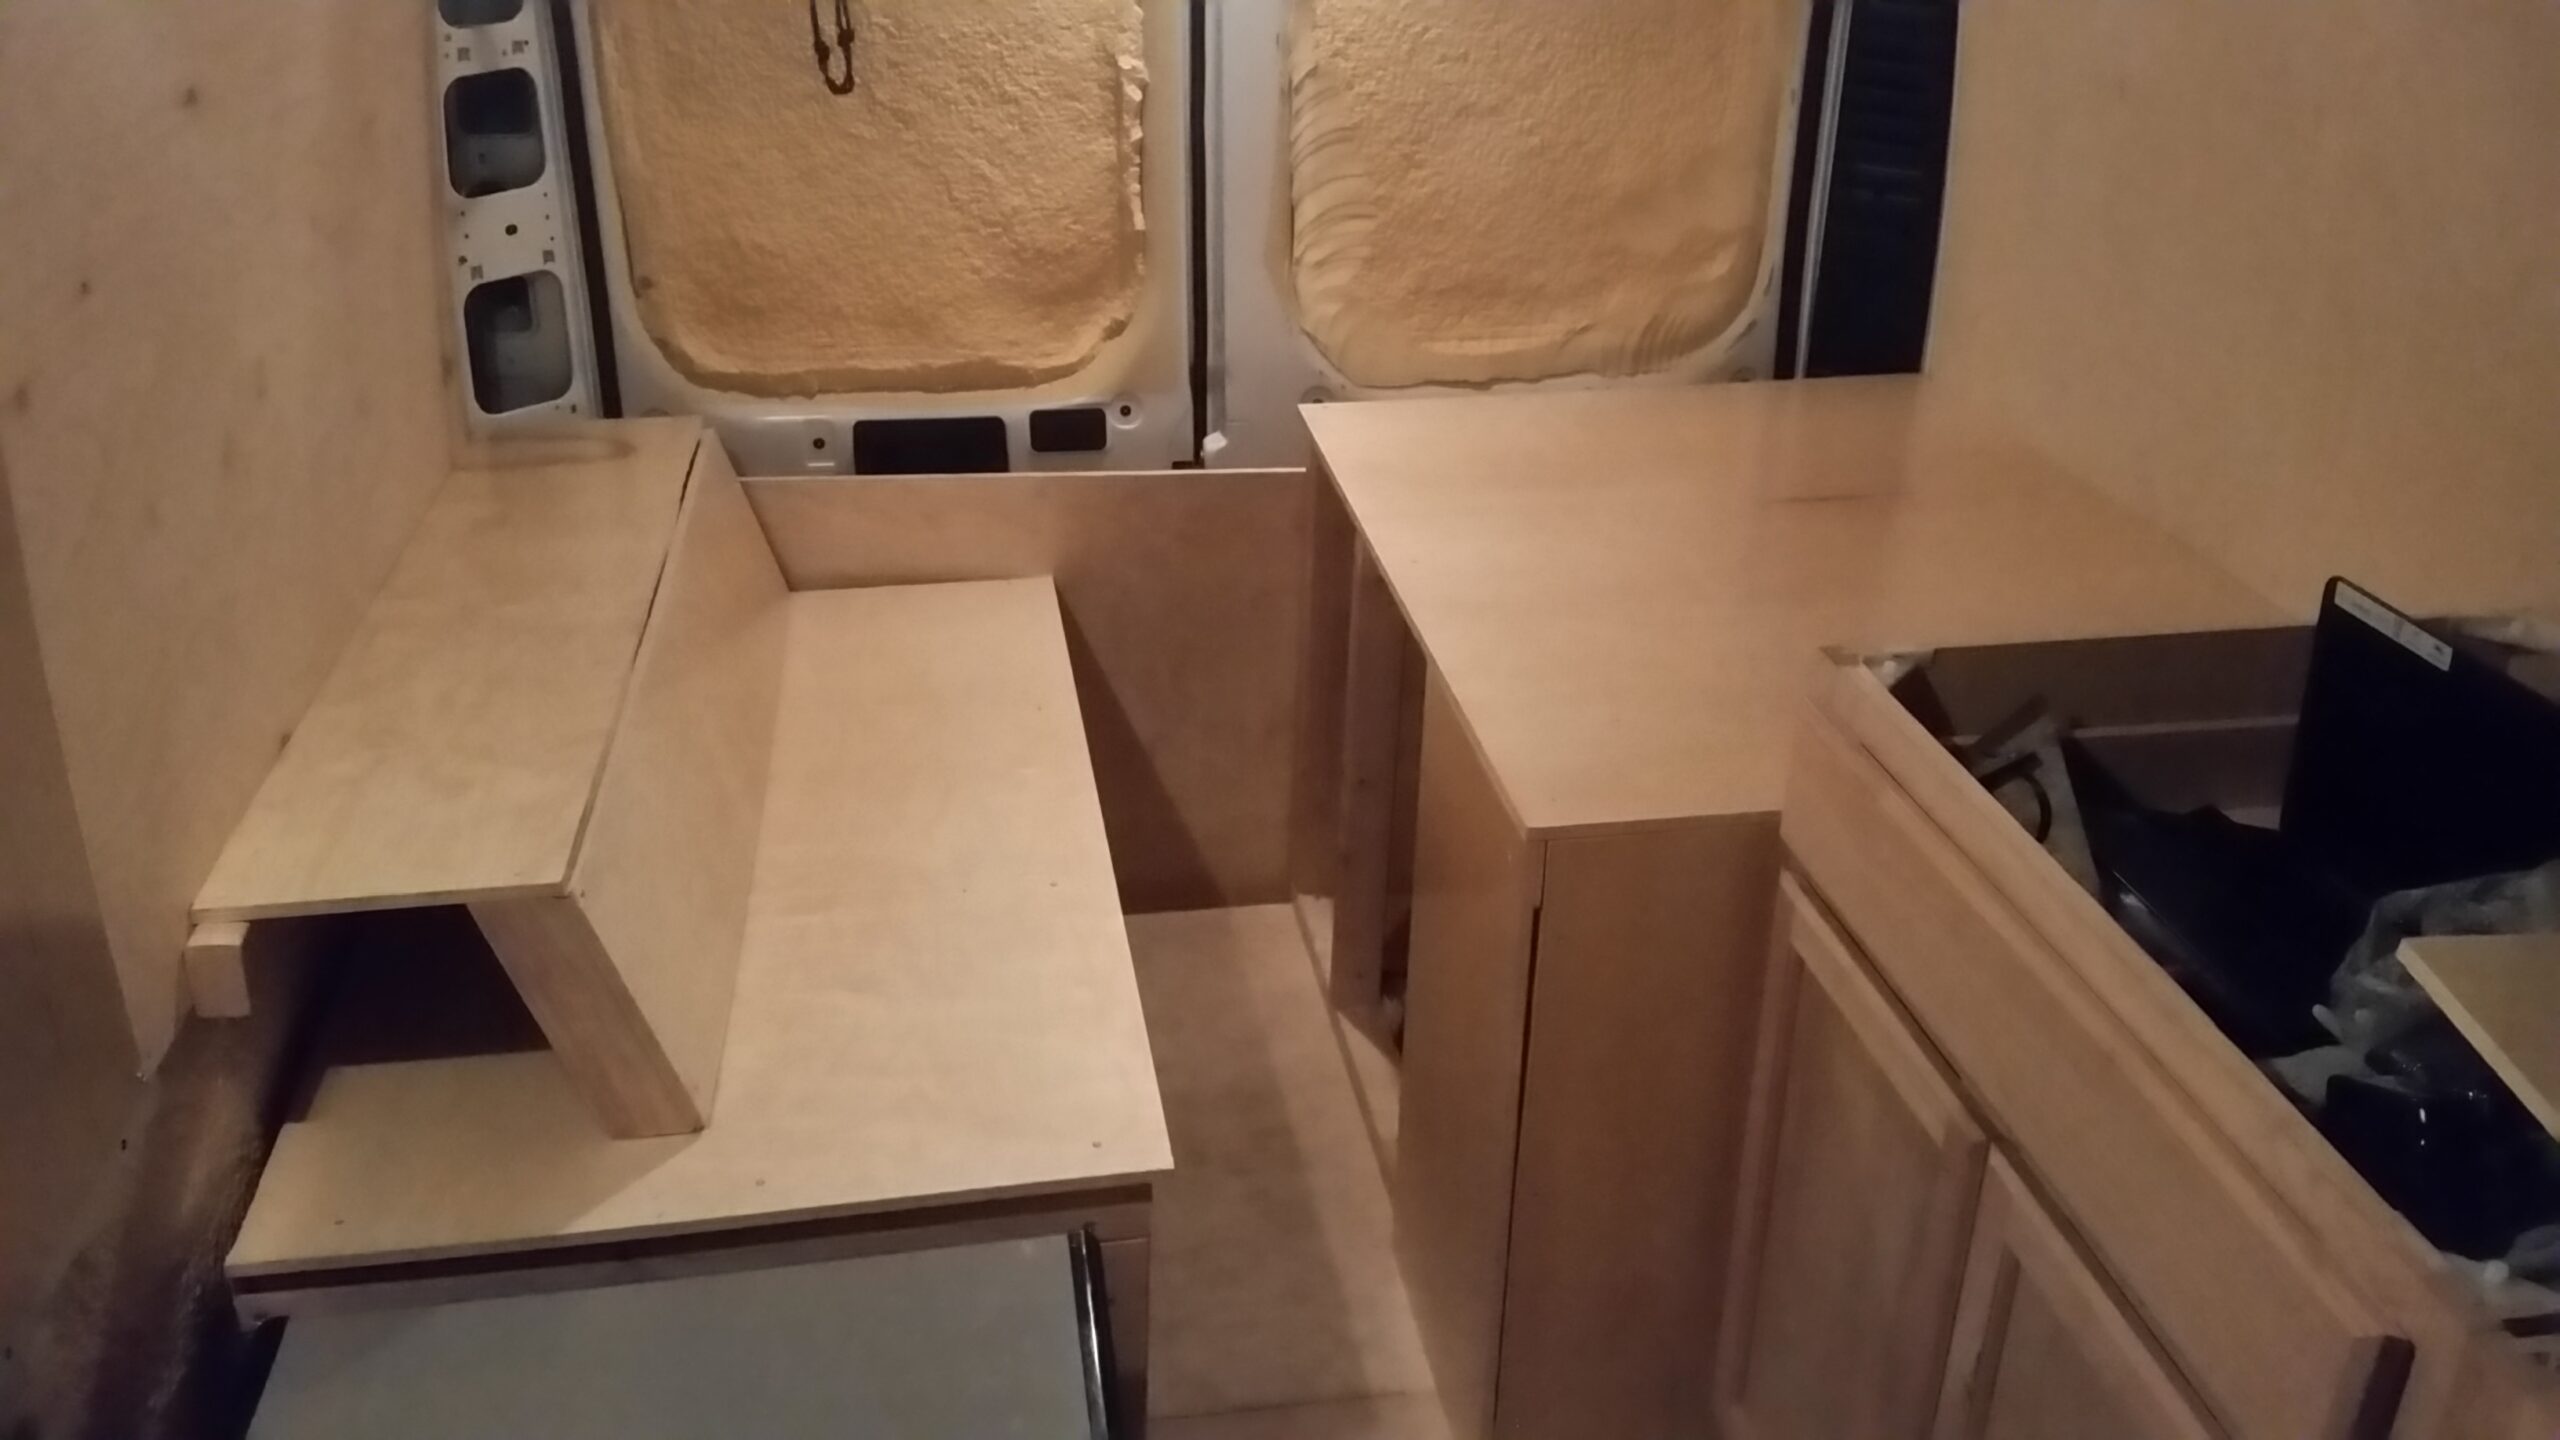
But a newer, empty van without any amenities doesn’t quite make a person whole, and it wasn’t pretty. There were no string lights. There was no curated mountain backdrop.
It was not freeing. It was exhausting. And it didn’t even help me save.
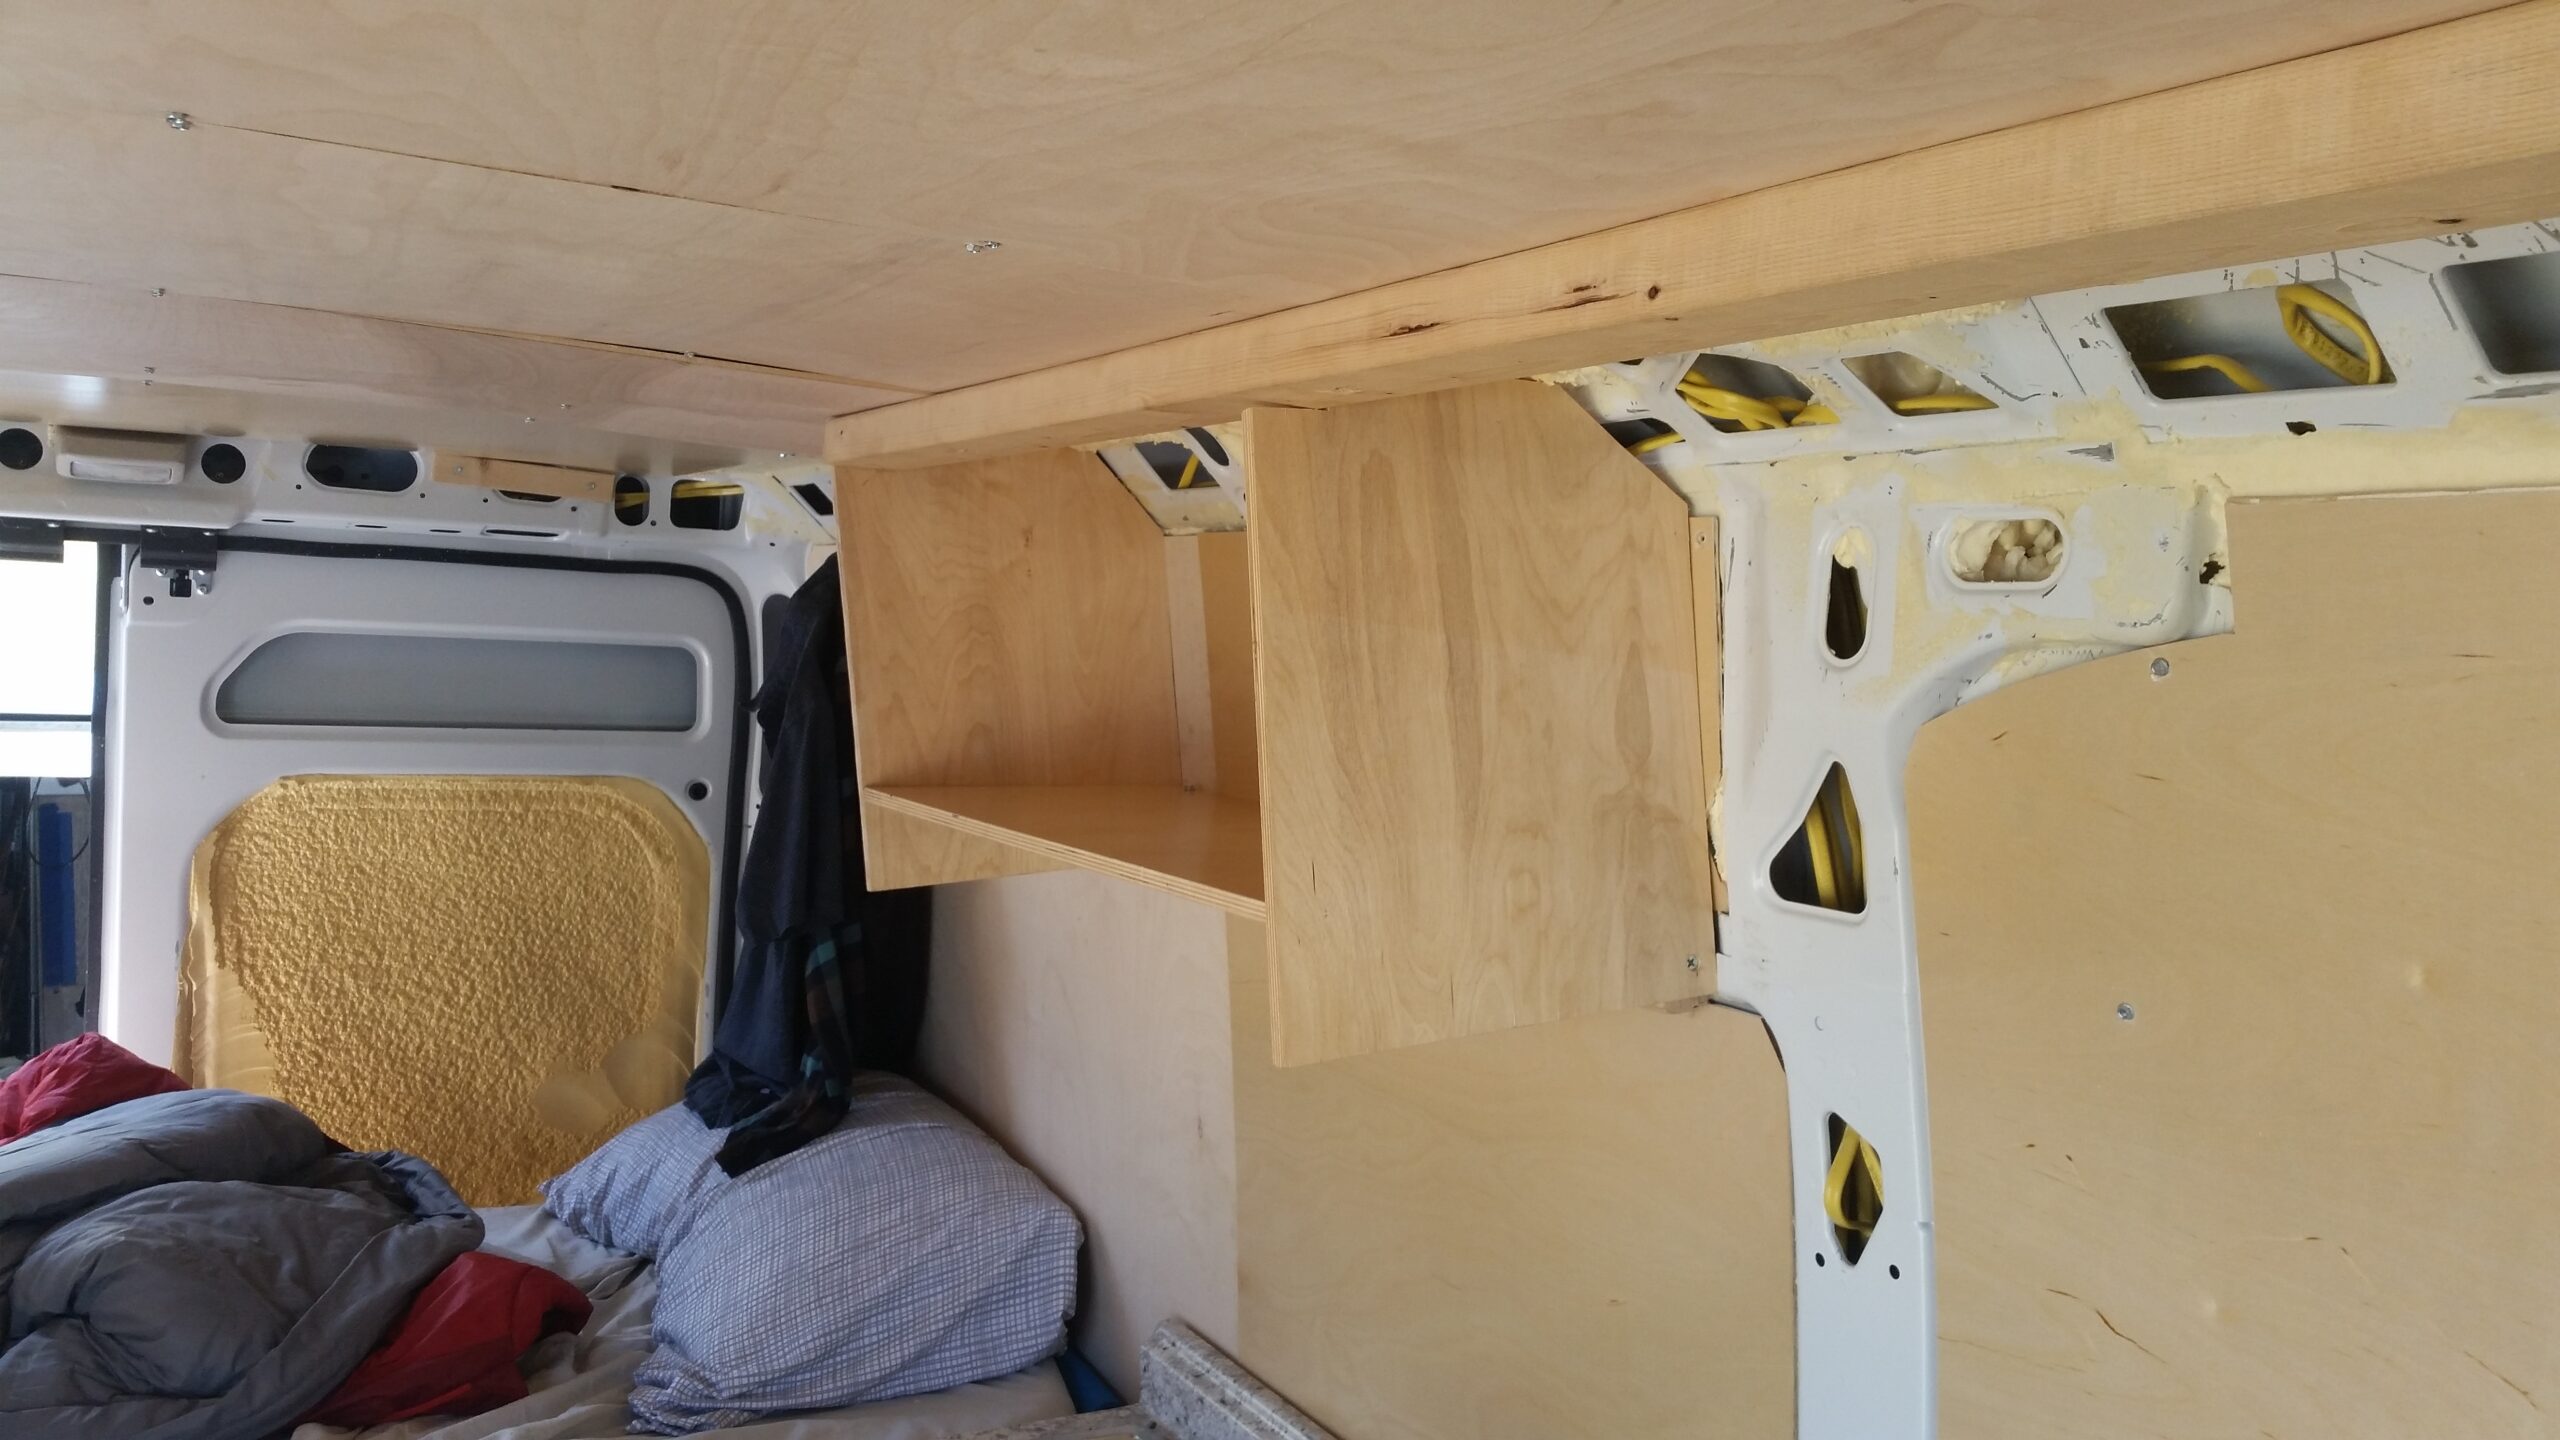
I took my time building that van out as best I could, but by the time my lease was up and I moved in, the reality was a sleeping bag, a parking-spot rotation I’d worked out by trial and error, and a routine of showering at the gym at night and using the bathroom at work in the morning to get presentable. I ate an unfortunate amount of Taco Bell and peanut butter sandwiches.
I had a small fridge but no real space or appliances for the basics, like cooking. I’d given up more than I realized to save on rent, and it wasn’t sustainable.
Van life as a lifestyle versus housing insecurity
I want to be clear about something: while I wasn’t truly homeless, I also wasn’t doing van life as a lifestyle experiment. I was, and had been for years, housing-insecure, and I was using the cheapest housing I could find to keep myself solvent while I tried to figure out what came next.
There’s a real distance between “minimalism is liberating” and “the math just doesn’t work this month.”
I was always on the wrong side of that line, and most of the budgeting and hustle rhetoric I heard came from people who’d never been on this side of the gap. Platitudes and formulas, none of it useful to me.
The van year ended, eventually, the way most bad situations end: I got tired enough of it to change something more drastic than the situation itself.
Move 2: out of my hometown (the unsexy answer)
I left the coast, my friends and family, the good weather. I moved to the Midwest. I had no job lined up, I knew no one, and I had barely anything to get me started (technically I had significantly more debt than I had assets at this time, so I actually had less than nothing to get started. That is modern American economics, for ya!).
This turned out to be probably the best of all the moves I made, but it was a major risk. My first piece of advice is obvious, and yet what it asks of you is something most people simply are not willing to consider.
The balance between cost of living and what you earn is not a constant. It’s a variable. And it’s the single biggest variable most aspiring homeowners refuse to touch.
In my old city a starter home cost roughly $700,000. In the Midwest it cost roughly $185,000. Same square footage, same number of bedrooms. The only thing different was the zip code, and the zip code was not paying my rent.
| Old coastal city | Midwest | |
|---|---|---|
| Starter home, same size and bedrooms | About $700,000 | About $185,000 |
| What I earned | $30,000 to $40,000 a year | $5,000 to $10,000 less |
| Difference in home price | Baseline | $515,000 less |
Earnings in my old city were relatively low too: $30,000 to $40,000 a year over the last three years, and that was with a college degree. So the value proposition was a $40,000 income against a home starting at $700,000. The high cost of living wasn’t offset by a higher wage.
Moving was hard. It took me away from friends, from a city I liked, from a job I was building. But the spreadsheet was unambiguous.
If I stayed, I’d be a permanent renter. If I moved, I’d be a homeowner within a year. How could I stay put?
And the math here worked. Within a year of moving to the midwest, I closed on a tiny single-family house, less than 800 square feet, the kind of place that looks like a starter cottage from the 1940s, because that’s exactly what it is. It wasn’t impressive. But it was mine, and I was building equity.
That house was always a stepping stone, but it was also a massive leap. 2,000 miles from home, from a sleeping in a van to my own house. I don’t want to downplay that. Three years later, I sold the starter-home, and bought my duplex.
The morning the duplex showed up in the spreadsheet
Even after I got into my first home, I’d take a little time most mornings to look at Zillow listings for fun and run the numbers on places I was interested in. I do this the way other people scroll Instagram: same pleasure and pain circuit, different inputs.
It wasn’t great feedback.
It looked like I’d be in that starter home until the end, or near it. That was not the idea I had when I moved across the country.
So one Sunday morning, sitting on my Facebook marketplace couch by the window, with some coffee, I expanded my criteria and looked at condos, MFH, land, etc. A local duplex listing caught my eye. I made a few adjustments to my spreadsheet and plugged it in, with the idea that I’d have two units. I’d live in one. The other unit’s existing rent would cover a significant chunk of the mortgage.
The number that came back didn’t look like a fantasy. It looked like my actual housing cost would be lower than the rent on one of the slum apartments I’d lived in in my early 20s.
Finding out what a house hack was
I read it twice. I built a more careful model. I started looking into FHA loans for owner-occupied multifamily financing, and came across the term house hack, which I’d never heard before despite a year of looking at real estate.
The financing programs that existed for someone in my position were significantly more generous than the ones for an investor buying the same property as a pure rental, because it would be my primary residence. Less cash down, favorable local property tax rules.
That’s when I started looking at duplexes seriously. About six months later, I closed on my current duplex.
What changed in my thinking at each pivot
Financial Freedom was worth major sacrifices. When you’re broke, the flow of money feels like weather. It rains, it doesn’t, you don’t control it. And that isn’t ideal for most people, but our priorities are elsewhere- hobbies, friends, family, etc., and these can keep you in the same situation financially if you never take a moment to evaluate. Being chained to rent and poverty, for me, became intolerable, it wasn’t something I could continue to endure.
The balance between the cost of living and what you earn is not a constant. It is a variable, and it is the biggest one most aspiring homeowners refuse to touch.
Housing stopped being a fixed expense I had to accept. I’d treated rent like a utility bill, something I paid because I had to, in whatever amount the market demanded. Before I moved into the van, I was thinking about how I could “beat” that market.
Eventually I came to see the market as wrong for me entirely, and moving to the correct market as the better option. How much is cutting your housing cost by $515,000 worth when you make less than $50,000, compared to saving 10% of almost nothing? Especially when it requires no income increase?
Housing costs were my biggest obstacle, but they were also the variable I could move the most.
The standard playbook stopped being the only playbook. “Buy a house in your 20s and pay it off” doesn’t work for people who can’t afford a starter home in their city. “Save into a 401(k)” doesn’t work for people who can’t save.
The standard playbook assumes a starting line that not everyone shares. The math doesn’t care about the starting line, it cares about what you do with the inputs you actually have. Once I accepted that the playbook was optional, the moves got easier to make.
What I’d tell the van-year version of me
If I could get a 30-second window with the version of me eating Taco Bell in a parking lot at 11pm:
- I’d tell him the math wasn’t lying, and that nothing was going to come out of left field and change my situation.
- I’d tell him he’d have to take control of his life if he wanted change.
- I’d tell him the city he loves is also the city making his math impossible, and that the move he doesn’t want to make is the one that buys him everything else.
- I’d tell him to stop being embarrassed about being broke, because being broke is not a character flaw. It’s an arithmetic outcome, and arithmetic outcomes can be changed.
I’d tell him financial freedom was possible and that it is coming, but it’s not going to look the way he thinks. It’s not going to be a single triumphant moment. It’s going to be a couple of major sacrifices, a couple of shrewd decisions and a Sunday morning spreadsheet adjustment with the quiet realization that suddenly the numbers work for a path out.
That’s how it actually happened.
Want to see what the math looks like on a real duplex? Open the calculator. Want the full breakdown of my own deal, with actual numbers? That post is here.
From cargo van to duplex: the receipts
Going from a van to a duplex made me the first in my family to own property that pays for itself. That thread continues in building first-generation wealth.
If you want the practical version of this story, here is exactly how to buy a duplex and live in one side.
The stage-by-stage version of this, laid out so you can find where you are: the first-property roadmap.
See what this looks like on a building you could actually buy.
The free house hacking calculator. Put in a price, a rent and your loan terms, and it returns your monthly cost with the tenant rent counted.
Frequently asked questions
How long did it take to go from a van to a duplex?
The van-to-duplex path took less than five years, through two moves rather than a plan: first into a van to escape rent in a high-cost coastal city, then 2,000 miles to the Midwest, where a starter home cost roughly $185,000 instead of roughly $700,000. A small house came within a year of the move, and the duplex three years later.
Why move to a cheaper city to buy a home?
Moving to a cheaper city changes the one variable most aspiring homeowners refuse to touch: the balance between cost of living and income. Coastal earnings of $30-40k a year against a $700,000 starter home did not work; a Midwest job paying $5-$10k less against a $185,000 house did, a $515k difference in home price with no income increase required.
Is living in a van a good way to save money?
Living in a van was not the money-saver it looked like. Without space or appliances for basics, it meant a sleeping bag, gym showers, a parking-spot rotation and a lot of fast food, and it was exhausting rather than freeing. It also did not meaningfully improve savings; the move that did was leaving the high-cost city.
How did the duplex idea come up?
The duplex idea came from a Sunday morning spreadsheet. A local duplex listing, plugged into the same model used for single-family homes with the other unit’s existing rent covering part of the mortgage, returned a housing cost lower than the rent on an early-twenties apartment. That led to FHA owner-occupied financing, the term house hack, and a closing about six months later.
Get started with the newsletter!
Useful, relevant analysis, tools, tricks, and what you need to know on the journey to financial freedom. From the van years to a duplex, the plain math and none of the hype.
Subscribe and get the free $0-to-First-Property Roadmap to start.
No spam. Unsubscribe in one click.
Want the deeper toolkit? The guides and spreadsheets are in the shop, from $5, and the free tools stay free either way.