
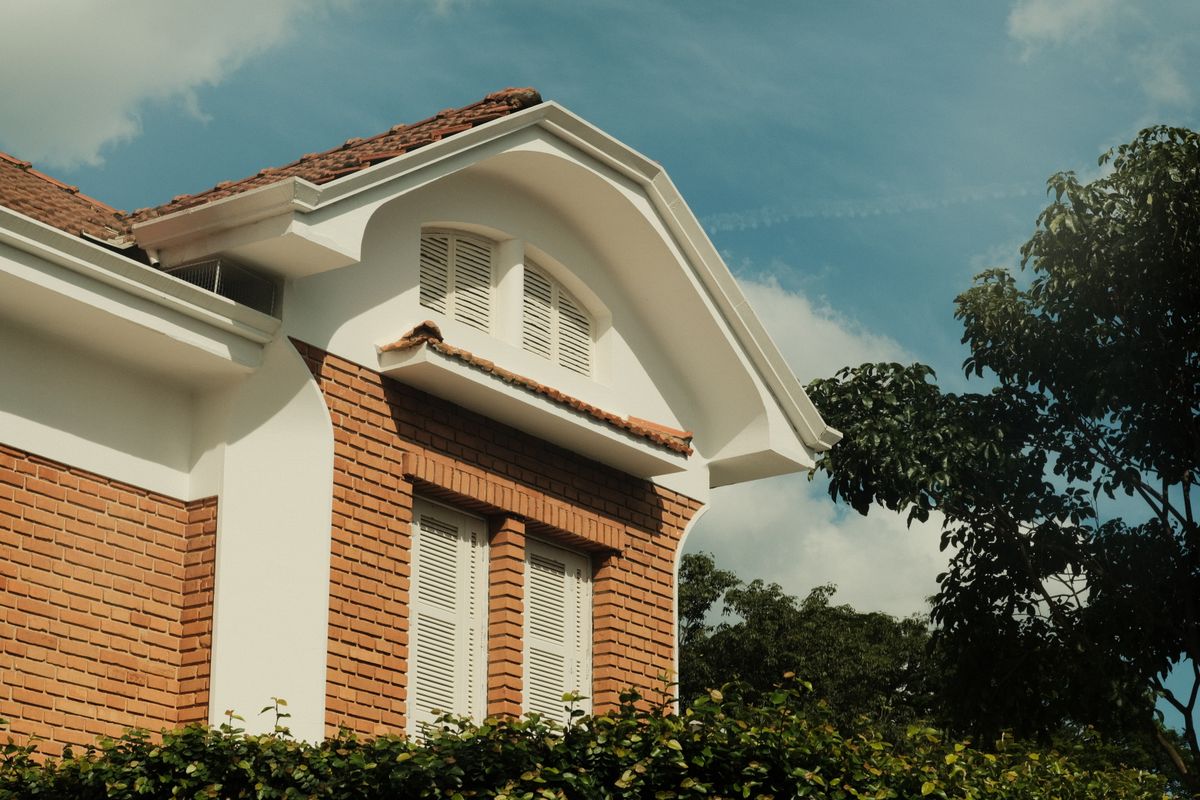
Here are the actual figures from year one of my duplex. I bought it in 2021 for $470,000 using an FHA loan with 3.5% down, which was $16,450, at a rate under 4% over 30 years. My total monthly payment including taxes and insurance is about $2,900. The upstairs tenant pays $1,100 (that was the year-one rent; the same unit is at $1,200 today) and the basement short-term rental averages about $1,000, so the property pulls in about $2,100 a month. (These are year-one numbers; rent has since risen, and the current figures are on the effective housing cost page.)
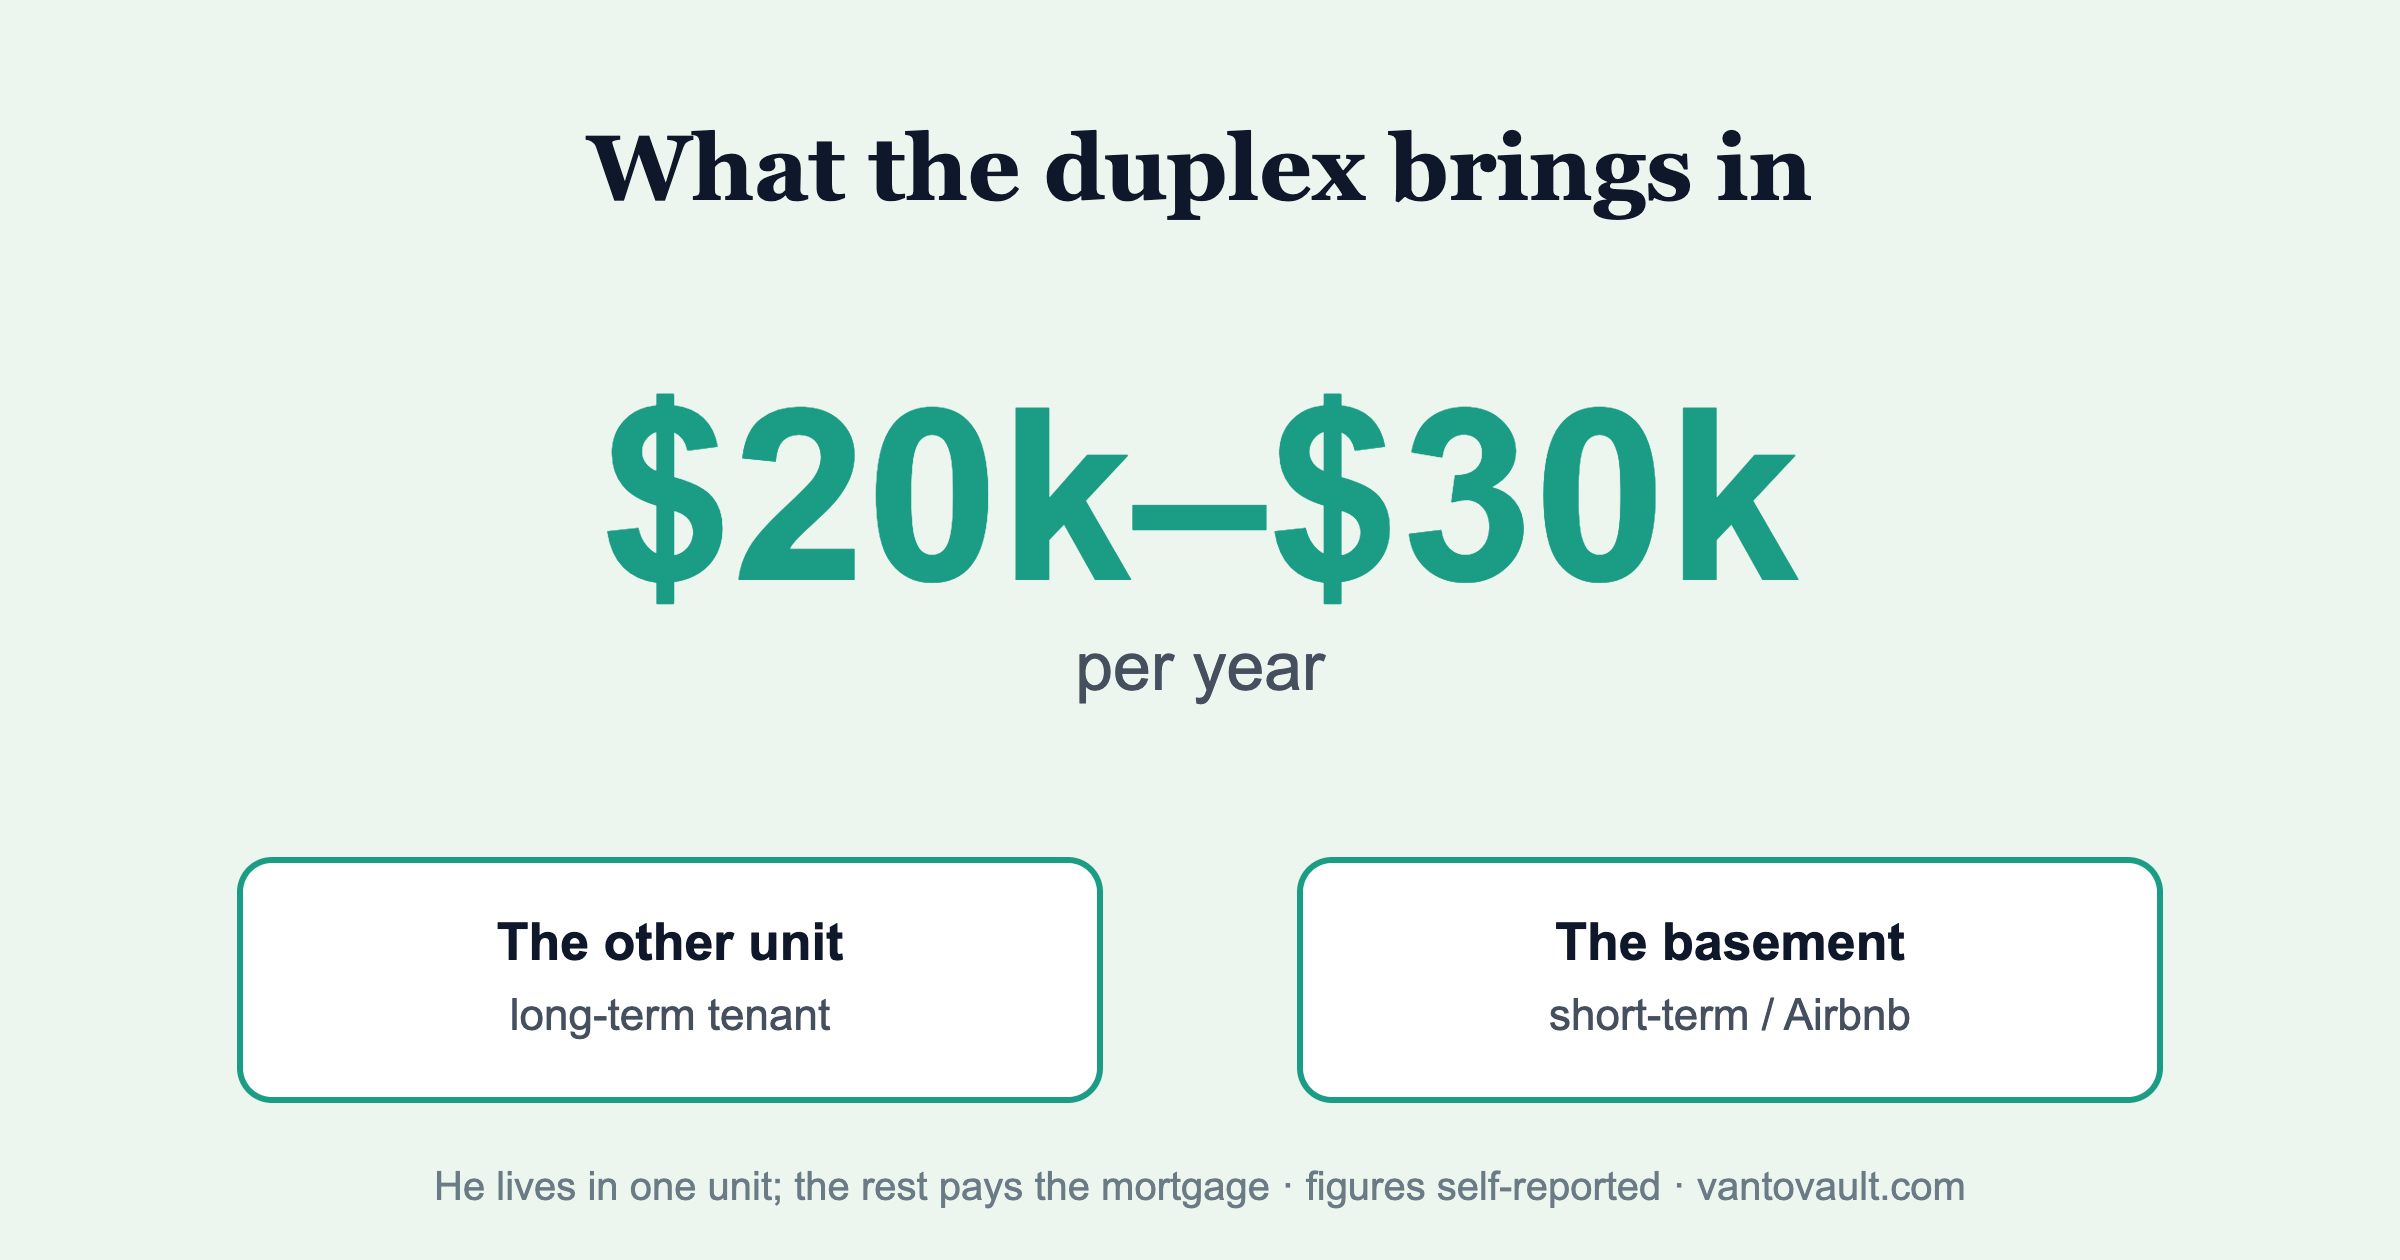
My receipts: the first duplex I house-hacked. Purchase price, financing, rent, expenses, surprises, and what I’d do differently.
A few of these numbers are rounded for privacy, and one operating line (a normal year’s repairs) is a reasonable estimate rather than an exact figure.
What the duplex looked like at purchase
I bought a side-by-side duplex in a working-class neighborhood in a midsize Midwestern city. Built in 1925, so nearly a century old, with all the character and all the repairs and maintenance that implies. Two units, plus a semi-finished basement with a separate entrance that the previous owner had used commercially (mostly storage, or so it seemed).
The property had been on the market for about 90 days. The previous owner was a landlord who had lived in and managed it and was ready to be done with it. The upstairs unit had previously had a tenant but now that, along with everything else, was vacant.
A few things drew me in:
- It was priced for the market, not above it. Sellers who price their property accurately tend to be realistic in negotiations.
- The bones looked OK, on paper. I was told the roof had 8–12 years left and the boiler had been “reconditioned.” (Both turned out to be optimistic.)
- The basement was a wildcard. Most buyers were probably looking at it as storage/major project. I was looking at it as a third income unit if I could get it furnished and running as a short-term rental.
- The location, for rent, was ideal. Shops and restaurants as well as mass-transit options nearby. Per the previous owner, the building had a strong record of rent.
FHA financing and the monthly payment breakdown
Here are the numbers as they came together at closing, in 2021.
- Purchase price: $470,000
- Loan type: FHA (owner-occupied small multi)
- Down payment: 3.5% = $16,450
- Closing costs: $0 out of pocket, the seller covered them
- Total cash to close: ~$16,450
If you ran a property like this through the calculator, this is roughly what you’d see, these are the inputs that determined whether the deal was worth pursuing.
Loan terms
FHA, owner-occupied. The 1.75% upfront MIP (~$7,900) was financed into the balance.
Monthly payment (PITI)
A note for the FHA nerds: FHA also charges a 1.75% upfront mortgage insurance premium (~$7,900 on this loan), which I financed into the balance rather than paying in cash. Folding that in nudges the real P&I up by about $34/month. I’m showing P&I on the base loan above for legibility. The tax, insurance and MIP lines in this box are the escrow amounts set at closing in 2021; the P&L below shows what insurance actually cost in a normal year, about $2,000.
This was actually my second home. I bought my first place, a tiny single-family starter home for $185,000, a few years earlier, and the equity from that sale funded this down payment. That’s the quiet engine of the whole journey: one modest, affordable purchase became the launchpad for a bigger one. (That starter-home story is its own post.)
Finding a tenant and adding a basement rental
I immediately started searching for a tenant, screened applicants, and we had an agreement fairly quickly. That took care of the upstairs unit.
The basement project started early. The previous owner had treated it as commercial interest/storage. I confirmed the setup with the city (how it was zoned), fixed quite a bit of what was broken, some of which required permits and skilled trades (plumbing, in this case). I then furnished it, and got it running as a short-term/midterm rental. Total upfront investment in the basement conversion: roughly $30,000, material, updates, furniture, linens, kitchenware, a lockbox, supplies, and setup.
Once everything was running, this is what the property collected each month while I lived in the owner unit:
- Upstairs tenant rent: $1,100/month
- Basement short-term rental: $11,000–$15,000/year net of platform fees, call it ~$1,000/month on average
- Owner unit (mine): $0 income, but my housing cost was now mostly covered
So while I’m living here, the property pulls in about $2,100/month, against my ~$2,900 PITI. That makes my effective housing cost roughly $800/month on the mortgage side, before utilities, which I’ll get to.
Where each month’s money comes from, and goes
The two rents cover about $2,100 of the roughly $2,900 payment. You cover the remaining about $800. Your real housing cost while you live there.
Show the numbers
| Upstairs tenant rent | $1,100 |
| Basement short-term rental | $1,000 |
| Your share (effective housing cost) | $800 |
| Monthly housing cost | $2,900 |
| Principal & interest | $1,950 |
| Property tax | $450 |
| FHA MIP | $300 |
| Insurance | $200 |
The expensive surprises (because of course there were)
If you buy a 1925 building and tell yourself you’ll get through ownership without surprises, you are setting up an unpleasant conversation with yourself. Mine didn’t all hit in month one, they showed up over the first few years, but they’re part of the story, so here they are, in order of how much they stung.
- Surprise #1: the boiler (year one). The seller had it “reconditioned” the year I bought, which sounded reassuring and turned out to mean “kept alive one more season.” It didn’t even make it through my first year, the original boiler had to be replaced outright.
- Cost: ~$20,000, in year one, right on top of the basement build-out. A reconditioned hundred-year-old heating system is still a hundred-year-old heating system.
- Surprise #2: the chimney (year four). This one I didn’t see coming at all. Three years in, the chimney turned out to be structurally broken.
- Quoted at ~$20,000 to properly repair. Rather than pour twenty grand into a chimney I didn’t strictly need, I had it safely closed off and capped for ~$5,000. Sometimes the right move isn’t to fix the thing; it’s to remove your dependence on it.
- Surprise #3: the roof. I was told it had 8–12 years of life left. In reality it was closer to 30 years old, effectively at the end. I started springing leaks here and there, which is one of the more stressful experiences I’ve had as an owner.
- A couple of years after I bought, and prior to the leaking, a hailstorm did enough damage that insurance found the hail to have damaged the roof, the windows and even ac units, which I hadn’t noticed. Since the hail damaged the roof so much, insurance covered the replacement.
The lesson I keep relearning: if you’d run this property through the calculator with a 5% maintenance reserve, you’d have been badly short. Model maintenance high, 12–15% of rent, more on anything this old, and get your own trades to inspect the big systems, not just the general home inspector who flagged the boiler and roof as “fine.”
First-year income and expenses on the duplex
Here’s a representative stabilized operating year, rounded, while I’m living in the owner unit and self-managing.
I’m showing a normal year on purpose: my literal first twelve months also absorbed the ~$30k basement build-out and the ~$20k boiler, so year one’s actual cash outlay was brutal and unrepresentative. The big one-time capital hits are deliberately not buried in the operating numbers below, because smearing them into an “average” year would be exactly the kind of fuzzy math this site exists to call out.
Income:
- Upstairs tenant rent (12 months): $13,200
- Basement short-term rental (annual, net of platform fees): ~$11,900
- Total income: ~$25,100
Operating expenses:
- Property tax: $5,500
- Insurance: $2,000
- Utilities, I cover all of them for the entire building, my own unit included: ~$6,000
- Repairs & maintenance, normal year (estimated): ~$2,500
- Basement STR direct costs, cleaning, supplies, consumables: ~$1,000
- Property management: $0 (self-managed)
- Total operating expenses: ~$17,000
| Year one, the property’s own P&L | Amount |
|---|---|
| Net operating income (NOI) | About $8,100 |
| Debt service (P&I plus FHA mortgage insurance, 12 months) | About $26,900 |
| Pre-tax cash flow | About -$18,800 |
| Total cash invested (down payment plus basement setup) | About $46,450 |
| Cash-on-cash return | About -40% |
Before you close the tab: that negative number is the whole point, and it is not a bad deal. The property “loses” about $18,800 in a normal year on paper for two reasons.
I’m living in one of the units rent-free, so a third of the building produces no income, while I still pay the whole building’s mortgage and running costs. That’s not a leak, that’s the entire strategy.
The house-hack arbitrage doesn’t show up in the property’s cash flow line. It shows up in my housing line.
The full year: every dollar in, every dollar out
The rents brought in $25,100; I added $18,800 to cover the rest. On paper the property “loses” money: that’s the cost of living here while I build equity, and the one-time hits (the ~$30k basement build-out and ~$20k boiler) are deliberately kept out of this stabilized year.
Show the numbers
| Upstairs tenant rent | $13,200 |
| Basement short-term rental (net) | $11,900 |
| Your cash added | $18,800 |
| Cash through the property | $43,900 |
| Debt service (P&I plus FHA MIP, 12 mo) | $26,900 |
| Operating expenses, total | $17,000 |
| Property tax | $5,500 |
| Utilities (whole building) | $6,000 |
| Insurance | $2,000 |
| Repairs & maintenance | $2,500 |
| Basement STR direct costs | $1,000 |
The number that actually matters
Before the duplex, my housing cost was $1,500/month, the mortgage on that $185k starter home (and roughly what an equivalent rental would have run me).
After the duplex, my effective housing cost on the mortgage side is ~$800/month, because the tenants cover most of the payment.
Why the utility line is smaller than it looks
I pay all the utilities for the building, about $6,000 a year, but that figure already includes my own unit’s usage, which I would be paying as any renter or owner anyway. The genuinely incremental cost of carrying the tenants’ utilities is only a slice of it.
Even counting the whole thing, I’m housing myself for dramatically less than $1,500 a month while building equity on a $470,000 asset (before the renovations) instead of a $185,000 one.
That’s the trade. A wildly “negative” property P&L, and a personal budget with hundreds of extra dollars in it every month and a much bigger asset compounding underneath me. If you only look at the property’s cash flow, you’ll talk yourself out of the best move available to you.
What I’d do differently
- I’d budget the basement conversion more conservatively. I underestimated costs and overestimated how fast bookings would ramp. If I’d modeled the basement at break-even for the first six months instead of profitable from the start, I’d have been more patient.
- I’d get the boiler and roof inspected by my own specialists, not just the general home inspector. The general inspector called the boiler “reconditioned” and the roof “8–12 years.” My own HVAC tech and a roofer would have told me the truth: one season of life left, and a roof that was actually 30 years old. That’s a $20k+ swing in how I’d have negotiated.
- I’d build the tenant relationship from week one. My upstairs tenant turned out to be great, but I didn’t foster the relationship as well as I could have, as I was somewhat awkward about them being my tenant and not also my neighbor.
- I’d model property management from day one, even though I don’t pay for it. The day I move out, that’s an 8–10% line item, if I choose to go that route. Pretending it’s $0 forever gives you a misleading read on the property’s standalone economics.
What I got right
- I bought a property whose math worked on conservative assumptions, not aggressive ones. I didn’t need a single basement booking for the deal to make sense as an owner-occupied house hack. The basement was upside, not the thesis, which is exactly why the surprises hurt my pride more than my solvency.
- I used FHA even though it meant permanent MIP. That $300/month of mortgage insurance is annoying, but the alternative was waiting years to save a 20% conventional down payment in a market that was appreciating faster than I could save. The MIP was the right trade.
- I funded it with starter-home equity, not a windfall. There was no inheritance to draw on, and no rich relative behind it. A modest $185k house, bought when I could finally afford one, turned into the down payment on a $470k one. That’s the boring, repeatable mechanism nobody puts in a thumbnail.
- I bought where the math worked, not where I most wanted to live. I’d still rather live back on the coast. But the math wouldn’t have worked there, and the math is what makes this site exist.
How to use this for your own deal
The point of showing my work isn’t to flex one deal, there’s nothing flex-worthy here. It’s a normal house-hack on a normal, century-old duplex with a broken chimney. The point is to give you a complete reference to hold up against your own numbers.
If you’re looking at a small multi right now:
- Run your listing through the calculator. If your projected cash flow looks much better than mine on similar assumptions, you’re probably missing an expense line.
- Model year-one with the surprises included. Add 1.5x your maintenance reserve. Old properties surface their problems early, and “reconditioned” is not a warranty.
- Run the long-term projection over a 5–10 year hold. A house-hack often looks unimpressive in year one and excellent in year five. That’s where it becomes legible.
- Reach out if you want a second pair of eyes. I won’t tell you whether to buy, that’s not my job. I’ll tell you whether your assumptions look reasonable, and where I’d push back if I were running the spreadsheet.
The companion post breaks down the eleven inputs and six outputs in more depth. If you’ve read this far, you’ll appreciate it.
Have a specific scenario you want me to run? Send it over. The more real listings I see, the more useful this site gets.
Photos of the duplex renovation
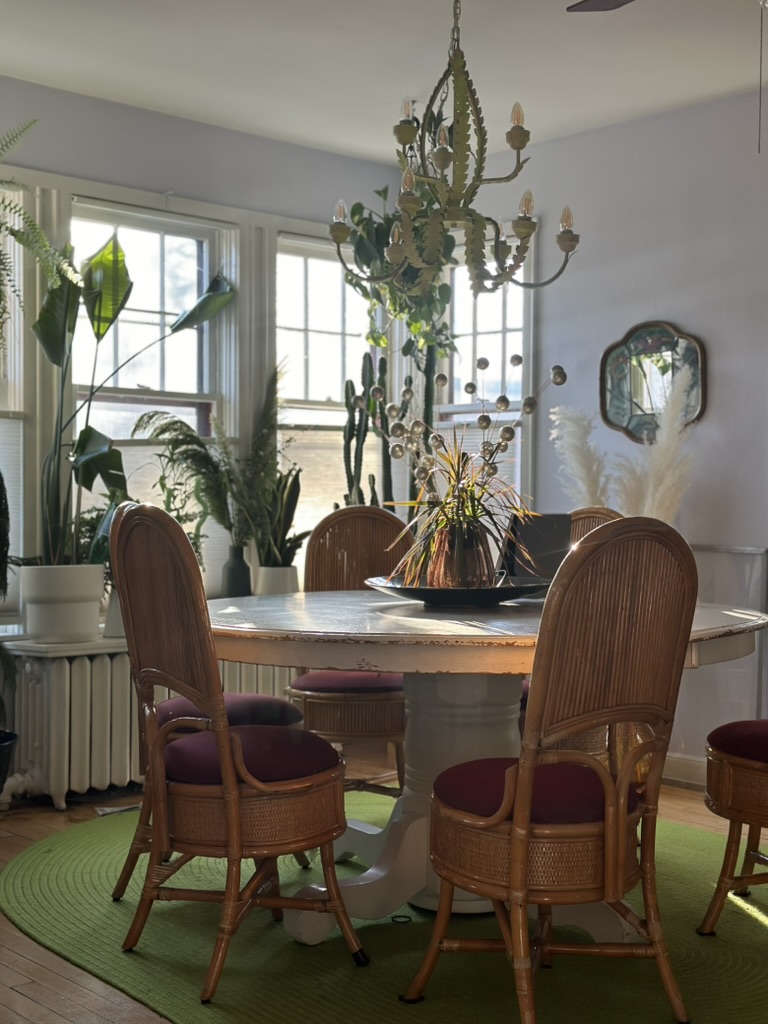
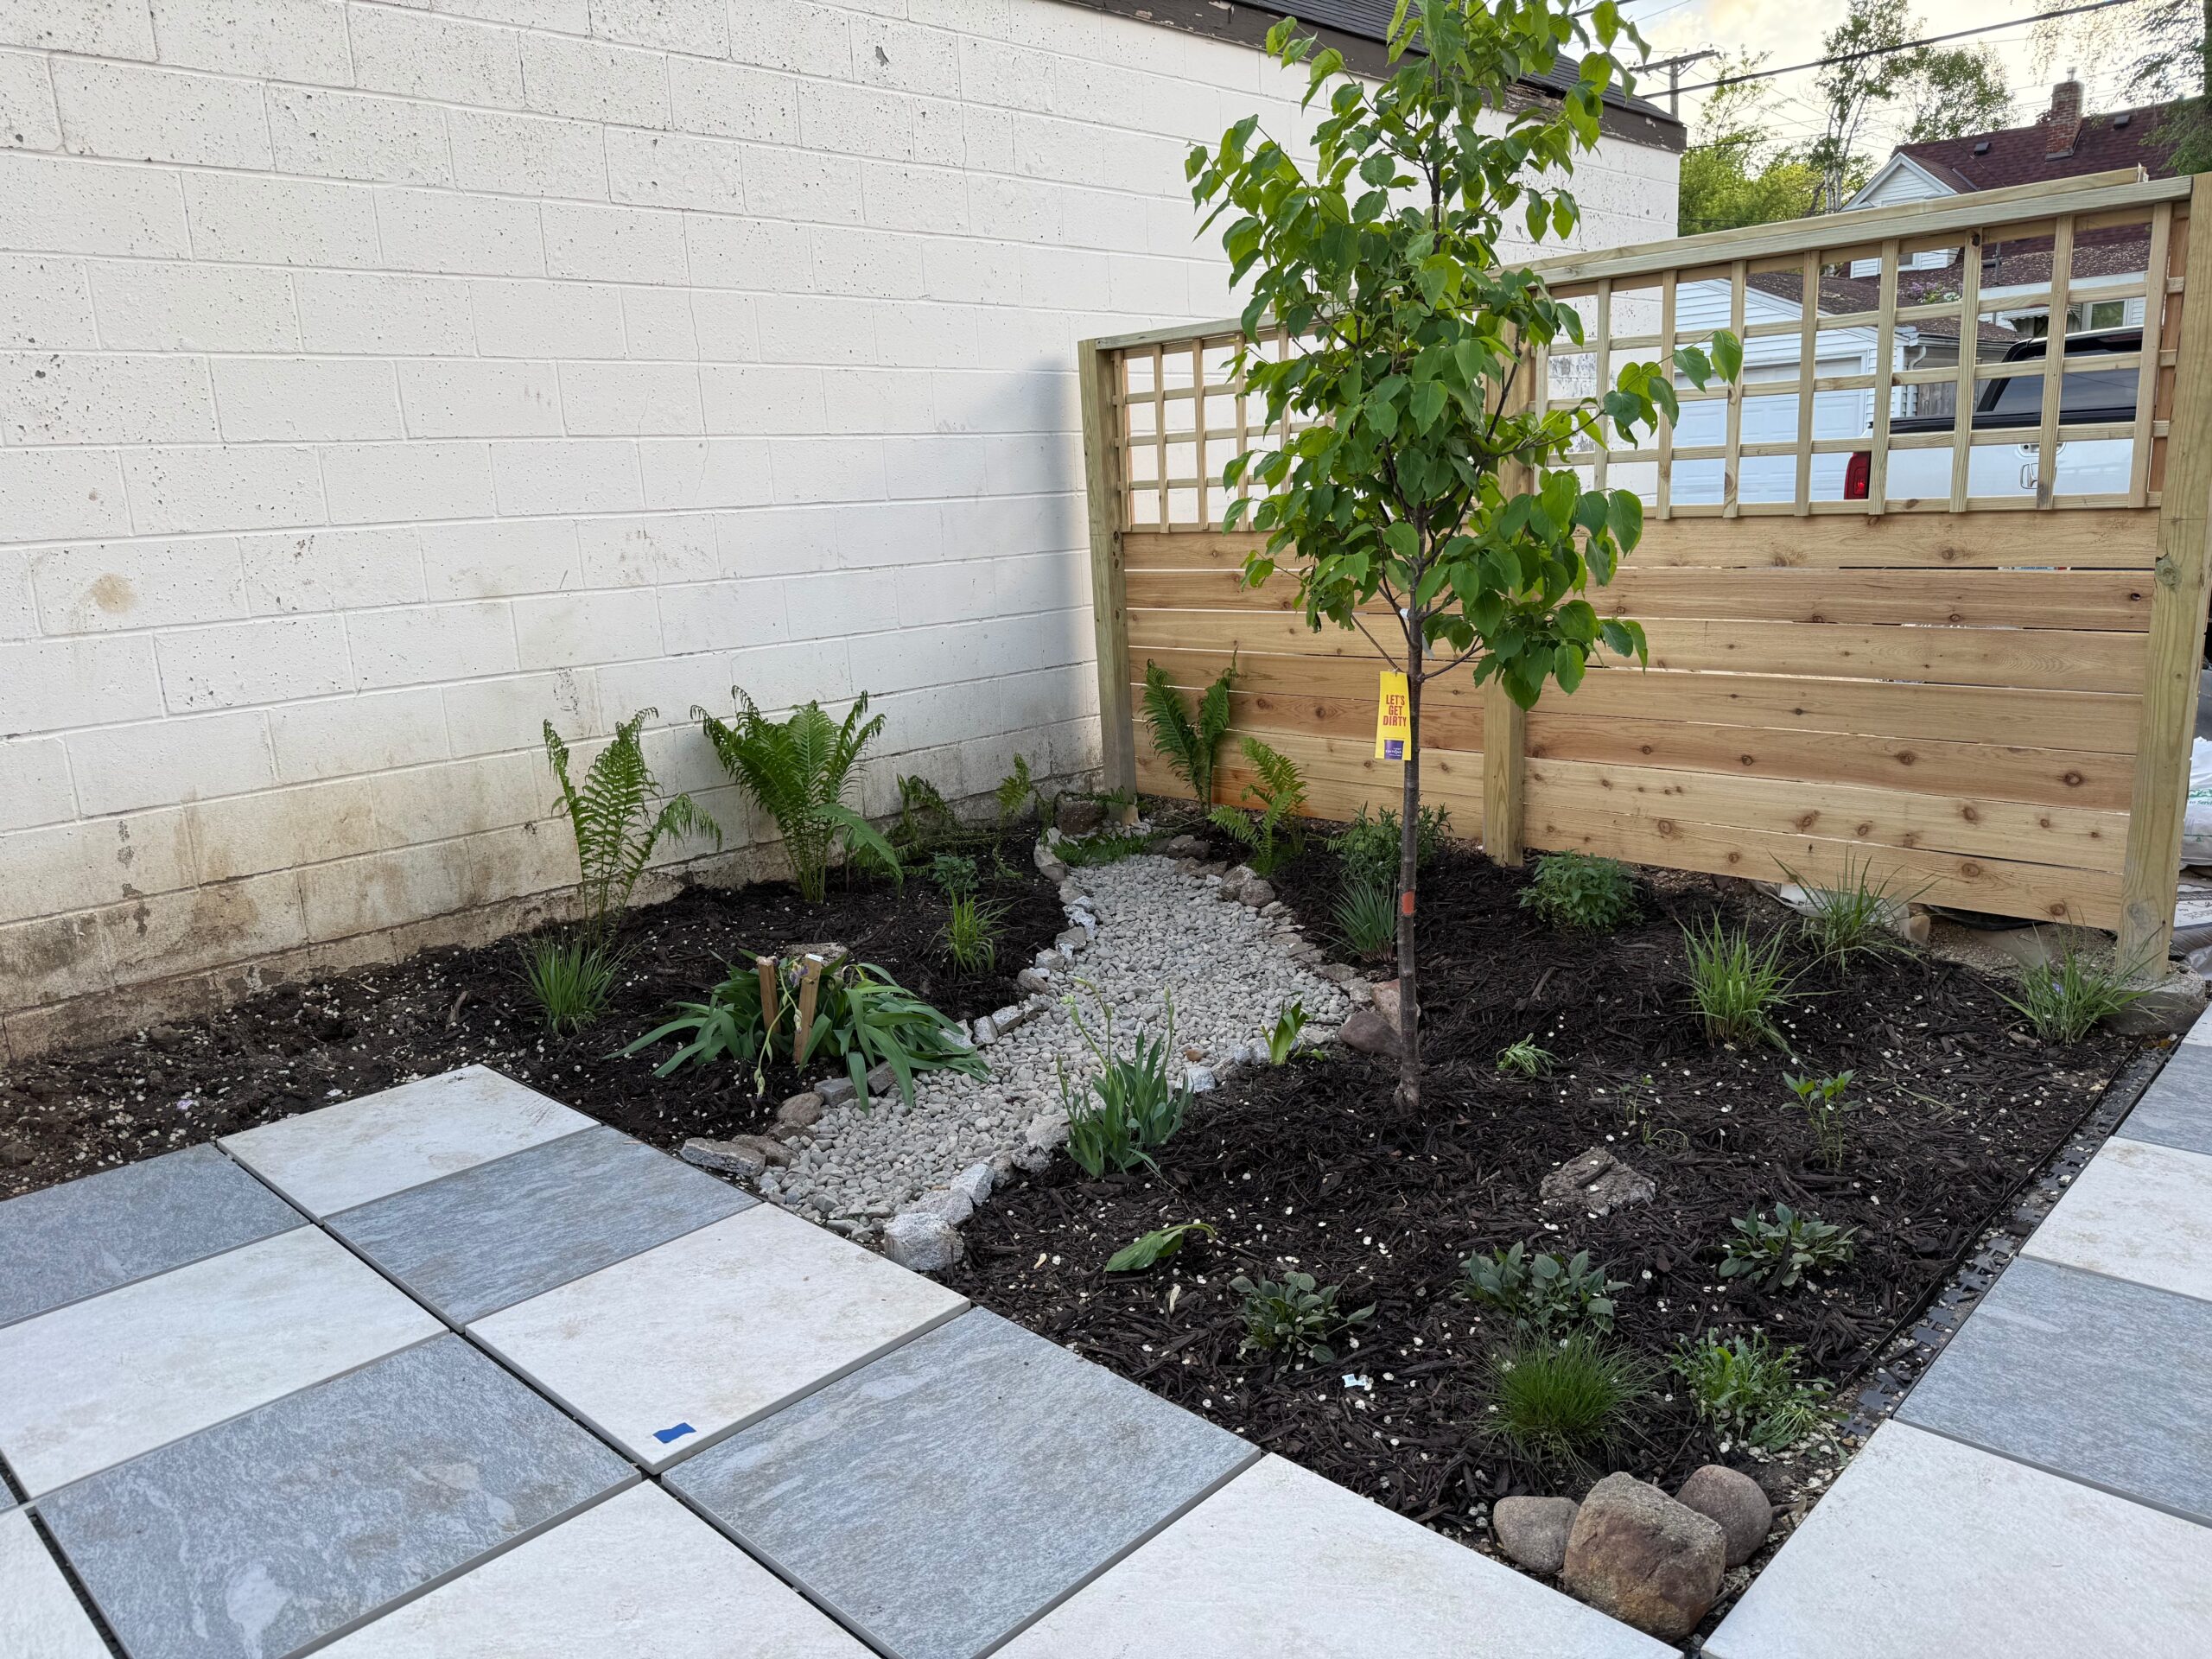
- The labor side of this year, told in pictures, is in the sweat equity post: the full inside and outside sequence, from bare dirt to finished.
- A companion to this one: what I underestimated buying my first properties covers the lines I got wrong rather than the ones I got right.
- The month-by-month version of the income side, twelve payouts against twelve payments, is in how much my tenants actually covered.
- The surprises above get their own post, with the first guest who ever booked and what I test before buying now: what went wrong after I bought the duplex.
See what this looks like on a building you could actually buy.
The free house hacking calculator. Put in a price, a rent and your loan terms, and it returns your monthly cost with the tenant rent counted.
Frequently asked questions
How much did the duplex cost and what was the down payment?
The duplex cost $470,000 in 2021, bought with an FHA loan at 3.5% down, which was $16,450, at a rate under 4% over 30 years. The seller covered closing costs, so total cash to close was about $16,450, funded by equity from the sale of a $185,000 starter home rather than a windfall.
What is the effective housing cost on the duplex?
The effective housing cost in year one was roughly $800 a month on the mortgage side. The total payment including taxes and insurance was about $2,900, and the upstairs tenant’s $1,100 plus the basement short-term rental’s average of about $1,000 covered about $2,100 of it, before utilities.
Why is the cash-on-cash return negative on a house hack?
The cash-on-cash return is negative, about −40% in the stabilized year, because the owner unit produces no income while the whole building’s mortgage and running costs still get paid. The property loses about $18,800 on paper while housing its owner for far less than the $1,500 a month the starter home cost, which is the whole point of the strategy.
What were the biggest surprises after buying the duplex?
The biggest surprises were a reconditioned boiler that failed in year one and cost about $20,000 to replace, a chimney found structurally broken in year four and capped for about $5,000 instead of a $20,000 repair, and a roof closer to 30 years old than the 8–12 years claimed. The lesson: model maintenance at 12–15% of rent on old buildings and hire your own trades to inspect the big systems.
Get started with the newsletter!
Useful, relevant analysis, tools, tricks, and what you need to know on the journey to financial freedom. From the van years to a duplex, the plain math and none of the hype.
Subscribe and get the free $0-to-First-Property Roadmap to start.
No spam. Unsubscribe in one click.
Want the deeper toolkit? The guides and spreadsheets are in the shop, from $5, and the free tools stay free either way.